
Key Takeaways
- Business use increases exposure, so commercial auto premiums are almost always higher than personal equivalents.
- Vehicle type, gross vehicle weight, and cargo affect rates as much as driver history does.
- A single at-fault driver in a fleet can raise premiums for the entire policy.
- Radius of operation is a major rating variable that sole traders often underestimate.
- Insurers treat the business itself, its industry class and years in operation, as a risk factor separate from the vehicles.
Commercial vehicle insurance rating
Commercial vehicle insurance rating is the process insurers use to calculate premiums for vehicles operated for business purposes. Unlike personal auto policies, commercial rating accounts for the vehicle's use, the business type, driver records across a fleet, and cargo or equipment carried. Rates reflect the higher frequency and severity of claims that business-use vehicles tend to generate.
Insurers file their rating algorithms with state departments of insurance, so the specific weighting of each factor can differ by carrier and state, even for identical vehicles and businesses.
Why commercial rating works differently
A vehicle used for business is not simply a personal car that happens to travel to a job site. Insurers treat it as part of a commercial enterprise, with its own liability profile. The moment a vehicle is used to transport goods, carry paying passengers, or service clients on a regular basis, it moves outside the scope of most personal auto policies.
Commercial rating starts from the same foundation as personal rating (vehicle value, location, driver history) but adds layers that do not exist in consumer policies: the nature of the business, how many drivers share the vehicle, what it carries, and how far it routinely travels. Each variable can move the premium materially, which is why two identical pickup trucks in the same zip code can carry very different rates depending on what business owns them.
For a broader understanding of how insurers build premiums across vehicle types, the practices behind managing auto insurance costs over time article covers how coverage decisions evolve with a vehicle's age and use.
Vehicle characteristics that drive the rate
Gross vehicle weight rating (GVWR) is one of the first figures an insurer examines. Light-duty trucks and cargo vans sit in a different risk class than medium-duty box trucks or heavy commercial vehicles. Higher GVWR means greater potential damage in a collision, higher repair costs, and larger liability exposure to third parties.
Body type and intended use follow closely. A refrigerated van, a flatbed, and a standard cargo van may share the same chassis but each carries a distinct risk profile based on what it hauls and how it is loaded. Specialty equipment mounted to a vehicle, such as a crane or aerial lift, is rated separately and typically requires additional endorsements.
Vehicle age affects physical damage premiums through actual cash value. As depreciation reduces a vehicle's market worth, the cost to insure it for collision and comprehensive coverage usually falls. The relationship between depreciation and insurance value matters here: an older work truck may warrant dropping certain physical damage coverages once its value drops below a practical threshold.
3x
Higher average claim severity for commercial vs. personal auto
Commercial auto liability claims tend to be significantly larger than personal auto claims, in part because business vehicles are involved in accidents during higher-traffic hours and often carry third-party cargo or passengers.
50+ miles
Radius threshold that shifts a vehicle to a higher risk tier
Many commercial rating systems treat operations beyond 50 miles from the business's home base as intermediate-range, triggering a higher rate class than local-only vehicles.
3 to 5 years
Loss run history period most insurers require
Commercial insurers typically request three to five years of prior claims history from the current or previous carrier before quoting a fleet policy.
Driver and fleet history
For a sole operator, the personal driving record carries significant weight. Moving violations, at-fault accidents, and DUI convictions in the prior three to five years all increase the rate. Commercial insurers often look back further than personal insurers do.
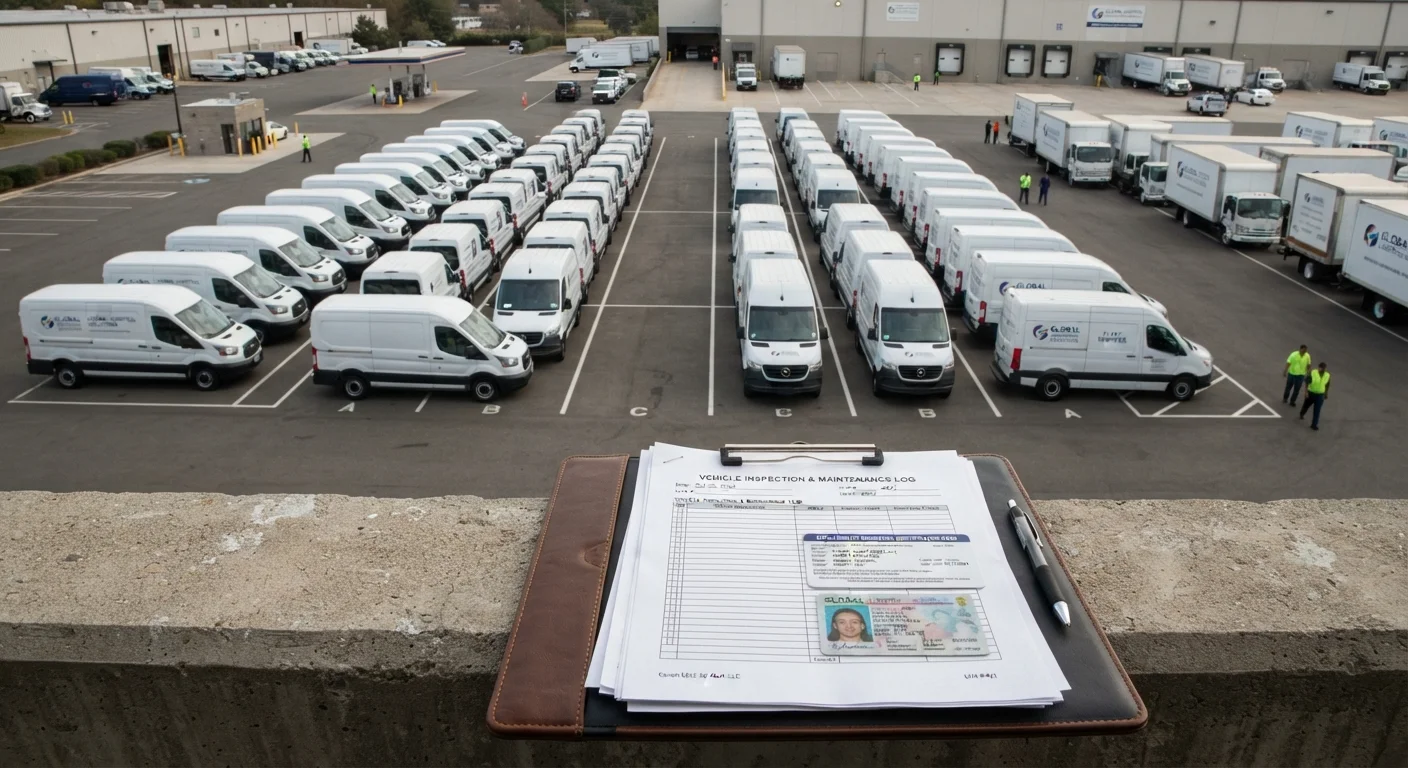
For a fleet with multiple listed drivers, the aggregate loss run, which is the documented claim history of the entire policy over three to five years, becomes the primary pricing signal. A single driver with a poor record can raise the cost for every vehicle on the policy. Insurers may require driver exclusions or impose surcharges for high-risk individuals rather than decline the fleet outright.
Some carriers offer usage-based insurance programs adapted for commercial fleets, where telematics data on speed, braking, and hours of service can be used to reward lower-risk driving behavior across the fleet.
Business classification and radius of operation
Insurers assign each business to an industry class code that reflects the typical risk of that type of operation. A landscaper, a courier service, and a mobile medical equipment supplier all use vans, but their liability profiles differ because their operations differ. The class code affects base rates before any vehicle or driver data is applied.
Years in business also factor in. A startup without a loss history is priced more conservatively than an established operation with five years of clean claims. This parallels how credit history works in personal auto rating, a topic covered in how credit scores feed into personal auto rates.
Radius of operation is the geographic range the vehicle regularly covers. Local service (under 50 miles from base), intermediate (50 to 200 miles), and long-haul (over 200 miles) each fall into separate risk tiers. Longer hauls mean more hours on varied roads, more overnight stops, and more jurisdictions, all of which increase exposure.
Keep a clean driver qualification file
Maintaining motor vehicle records for every listed driver, and pulling updated records annually, gives insurers evidence of active fleet management. Carriers often apply better rates to businesses that document their driver screening process rather than those that rely on self-reported histories.
Coverage structure and liability limits
Commercial policies typically carry higher minimum liability limits than personal policies, because accidents involving business vehicles frequently result in larger third-party claims. State minimums for commercial vehicles vary by vehicle class and, in many cases, by what the vehicle transports.
Coverage layers specific to commercial use include hired and non-owned auto coverage (for vehicles the business rents or employees use personally on business errands), cargo liability, and, for trucking operations, motor truck cargo coverage. Each layer adds to the total premium and is priced on its own terms.
Umbrella or excess liability policies are common in commercial fleets because a single serious accident can exhaust underlying limits quickly. The base commercial auto policy sets the floor; the umbrella sets the ceiling for total coverage. Understanding the full cost picture, including which coverages a business genuinely needs versus those it can reasonably forego, is where budgeting clarity begins.
This article provides general information about commercial vehicle insurance rating factors and is not a substitute for advice from a licensed insurance professional. Coverage terms, eligibility, and pricing vary by insurer, vehicle class, and state. Consult a licensed commercial insurance agent for guidance specific to your business and fleet.