
Key Takeaways
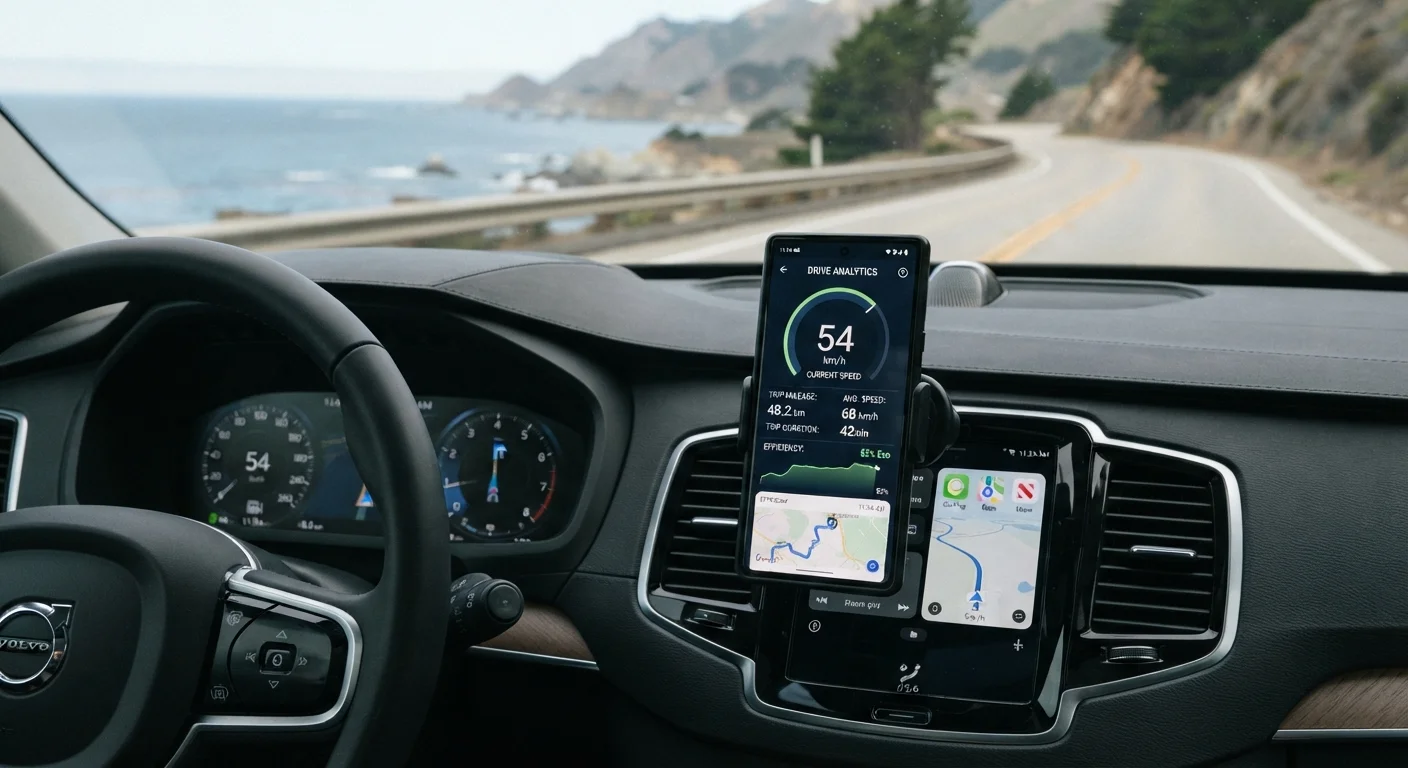
- Telematics programs use a mobile app or OBD-II plug-in device to collect driving data for premium calculations.
- Pay-per-mile programs charge a flat base rate plus a per-mile rate, so low-mileage drivers typically pay less.
- Monitored behaviors commonly include hard braking, rapid acceleration, phone use, and driving at night.
- Drivers who already have clean records may see modest savings; risky drivers can face higher rates in some programs.
- Data collection and privacy policies vary by insurer, so reading the program terms before enrolling matters.
Usage-based insurance (UBI)
Usage-based insurance is an auto policy where the insurer sets your premium based on how you actually drive, rather than relying solely on demographic and vehicle factors. Insurers collect data through a mobile app or a plug-in device and use it to calculate a discount or, in some programs, a surcharge. Pay-per-mile insurance is a specific type where the main variable is the number of miles you drive each month.
Telematics is the underlying technology: it combines GPS, accelerometer, and cellular data to transmit driving behavior in near real time to the insurer's scoring system.
How telematics programs are structured
Conventional auto insurance prices risk using factors like age, location, vehicle type, and driving history. Telematics programs add a real-time behavioral layer. The insurer gives you either a small plug-in device that connects to your car's OBD-II port (the same diagnostic port a mechanic uses) or a smartphone app. Both options transmit driving data back to the insurer continuously or in trip batches.
After a set monitoring window, the insurer scores your driving and applies a premium adjustment. In most U.S. programs, the adjustment is a discount off a standard rate. A minority of programs also allow surcharges for consistently poor scores, so confirming which model your insurer uses before you enroll is worth the time. Understanding how premiums and deductibles work together helps you evaluate whether a telematics discount actually changes your total out-of-pocket cost.
Check whether the program can raise your rate
Before enrolling in a telematics program, confirm whether poor scores can increase your premium or only reduce a potential discount. Some programs are discount-only, meaning your rate can only stay the same or go down. Others allow upward adjustments after the monitoring period.
What the data measures and why it matters
Insurers generally score four or five core behaviors. Hard braking (decelerating sharply) and rapid acceleration are the most common because both correlate with following too closely and aggressive driving. Speed is tracked, though most programs focus on the frequency of high-speed events rather than a single incident. Time of day matters because nighttime driving carries higher crash rates per mile. Some app-based programs also detect phone handling while moving.
Each behavior feeds a composite score. A driver who brakes hard frequently but drives mostly in daylight at low mileage will score differently than one with smooth inputs but a heavy highway commute at night. Insurers weight these factors differently, which is why two programs can produce meaningfully different discounts for the same driver.
~13,500
Average miles driven per U.S. driver annually
Federal Highway Administration data shows U.S. drivers average around 13,500 miles per year, a benchmark pay-per-mile programs price around.
20-30%
Typical telematics discount range advertised by insurers
Many U.S. insurers advertise potential discounts in this range for high-scoring drivers, though actual savings depend on individual program terms and driving data.
Pay-per-mile insurance: how the math works
Pay-per-mile programs use a simpler formula: a fixed monthly base rate plus a per-mile charge. If your base rate is $30 and your per-mile rate is $0.06, driving 500 miles in a month costs $60. Driving 1,200 miles costs $102. The base rate covers parked-car risks like theft or weather damage regardless of whether you drive.
This structure directly rewards low-mileage drivers. Someone who drives 4,000 miles a year will almost always pay less than under a conventional policy priced around the national average of roughly 13,000 to 14,000 miles annually. For context on how this fits into managing vehicle ownership costs, see keeping auto insurance costs manageable over time.
Who tends to benefit and who does not
Low-mileage drivers are the clearest beneficiaries of pay-per-mile programs. Remote workers, retirees, urban residents who drive infrequently, and households with a second car that rarely moves all fit this profile. For them, paying for the miles they actually log rather than a flat rate built around average mileage can produce real savings.
Behavior-based programs suit drivers who already practice smooth, attentive driving. If your daily commute involves a lot of hard stops in stop-and-go traffic, the telematics score may not reflect your actual risk level accurately, and your discount may be smaller than expected.
Drivers who cover high annual mileage at unpredictable hours are less likely to benefit from either program type. A long-haul commuter driving 25,000 miles a year will face a high per-mile bill under pay-per-mile programs, and extensive nighttime or highway driving can suppress telematics scores even with otherwise careful habits. Those drivers may find that standard pricing, adjusted through other levers, works out lower. Common insurance myths sometimes include the idea that telematics programs always save money; the reality is that savings depend heavily on individual driving patterns.
This article is for general informational purposes only and does not constitute personalized insurance or financial advice. Policy terms, data practices, and pricing structures vary by insurer and by state. Read program disclosures carefully and consult a licensed insurance agent for guidance specific to your situation.