
Key Takeaways
- Medical evacuation alone can cost $50,000 or more without insurance coverage.
- Trip cancellation fees, baggage loss, and liability exposure add up beyond medical costs.
- Domestic health insurance rarely covers emergency care abroad.
- Travelers who skip coverage absorb 100% of unexpected costs out of pocket.
- Understanding the risks helps you decide what level of protection fits your situation.
Short-term savings on premium costs
Skipping a policy saves the upfront cost, which for a basic single-trip plan can range from roughly 4% to 10% of total trip cost. For travelers with low-risk, low-cost trips, that saving is real.
Existing coverage may partially apply
Some credit cards include trip cancellation or baggage protection as a cardholder benefit. Homeowners or renters insurance sometimes covers personal property stolen abroad, reducing (though rarely eliminating) the gap.
Simpler logistics for straightforward trips
A domestic weekend trip with refundable bookings carries limited financial exposure. In that narrow scenario, the administrative overhead of comparing and purchasing a policy may genuinely outweigh the benefit.
Medical evacuation costs can be catastrophic
Air ambulance transport from an international destination to the U.S. can exceed $100,000. Without evacuation coverage, that bill falls entirely on the traveler or their family.
Nonrefundable trip costs disappear with cancellation
Prepaid flights, hotels, tours, and cruises are often nonrefundable. A covered emergency without a policy means absorbing those costs with no recourse.
Domestic health insurance rarely covers foreign care
Most U.S. health plans have very limited or no international coverage, and Medicare provides essentially no benefits abroad, leaving travelers to pay out-of-pocket for any care received.
Personal liability abroad is unpredictable
Accidents involving injury to others or damage to property in foreign countries can result in legal and financial obligations that a traveler's home liability coverage does not extend to.
Baggage loss recovery is limited without coverage
Airline liability for lost checked bags has regulatory caps that may be far below the actual value of the contents. Without travel insurance, recovering the difference depends entirely on the airline's goodwill.
Our Verdict
Traveling without insurance is a financial gamble that extends well beyond medical emergencies. Trip cancellations, evacuation costs, lost belongings, and personal liability can each produce bills that dwarf the cost of a policy. Whether coverage makes sense depends on trip length, destination, health factors, and how much financial exposure you can absorb.
Travelers taking short domestic trips with fully refundable bookings and strong existing coverage may find the risk tolerable, but anyone traveling internationally or with significant prepaid costs should review their exposure carefully before departing.
What travelers actually risk when they skip coverage
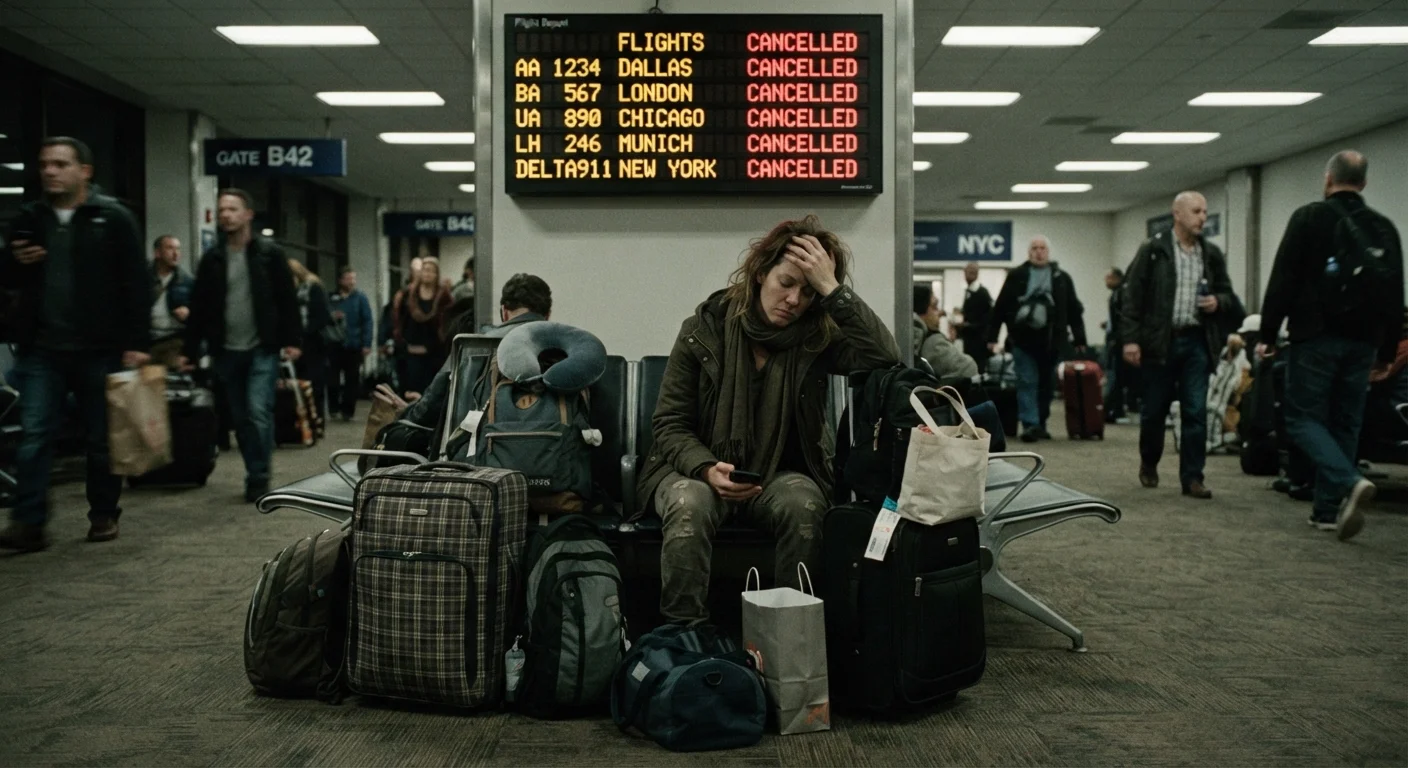
Most people who travel without insurance think of one scenario: getting sick and needing a doctor. The actual list of financial exposures is longer. A canceled flight, a missed connection that voids a prepaid tour, a stolen laptop, or a fender-bender with a rental car can each produce costs that no traveler budgeted for.
The hidden costs of popular tourist destinations are already easy to overlook. Add an uninsured travel disruption and those gaps multiply fast. Before deciding to skip coverage, it helps to map out exactly what you would pay in a realistic bad scenario, not just a worst-case one.
Short-term savings on premium costs
Skipping a policy saves the upfront cost, which for a basic single-trip plan can range from roughly 4% to 10% of total trip cost. For travelers with low-risk, low-cost trips, that saving is real.
Existing coverage may partially apply
Some credit cards include trip cancellation or baggage protection as a cardholder benefit. Homeowners or renters insurance sometimes covers personal property stolen abroad, reducing (though rarely eliminating) the gap.
Simpler logistics for straightforward trips
A domestic weekend trip with refundable bookings carries limited financial exposure. In that narrow scenario, the administrative overhead of comparing and purchasing a policy may genuinely outweigh the benefit.
Medical costs abroad: why domestic coverage often falls short
A common misconception is that a U.S. health insurance plan travels with you. Many plans provide little or no coverage outside the country, and Medicare does not cover care abroad in most situations. Even when a domestic plan does cover some overseas treatment, it typically requires you to pay upfront and seek reimbursement later.
Emergency medical evacuation is where costs climb fastest. Air ambulance transport back to the United States from Europe, Asia, or Latin America can cost anywhere from $50,000 to more than $200,000 depending on distance and medical complexity, according to figures cited by the U.S. State Department. That cost falls entirely on the traveler without dedicated travel medical or evacuation coverage.
Travelers with ongoing health needs face additional exposure. See our advance planning guide for health-specific travel for practical steps on managing medications and documentation before departure.
$50,000+
Minimum cost of medical evacuation abroad
The U.S. State Department notes that air ambulance transport from international destinations can range from $50,000 to over $200,000 depending on location and medical complexity.
4-10%
Typical travel insurance cost as share of trip
Travel insurance policies generally cost between 4% and 10% of total prepaid trip expenses, a figure cited widely by consumer travel and insurance information sources.
$0
Medicare coverage for most care outside the U.S.
The Centers for Medicare and Medicaid Services confirm that original Medicare does not cover health care received outside the United States in most circumstances.
Trip cancellation and interruption: the costs before you even board
Nonrefundable flights, prepaid hotels, tour packages, and cruise deposits can add up to thousands of dollars. If a trip is canceled because of a covered reason (serious illness, jury duty, a family emergency), a travel insurance policy may reimburse those costs. Without one, the money is simply gone.
Trip interruption is a separate exposure. If you have to cut a trip short after it starts, you lose both the unused portion of prepaid arrangements and the cost of last-minute flights home. Those unplanned one-way tickets are typically priced at a significant premium over advance fares.
The reasons travel budgets run short often include underestimating these potential losses. Travelers who feel financially tight on a trip already are rarely in a position to absorb a sudden $2,000 flight home.
Baggage, liability, and the risks people forget entirely
Lost, stolen, or damaged luggage is the disruption travelers report most frequently. Airlines have liability limits for checked baggage under the Montreal Convention, but those limits may not cover the full value of electronics, cameras, or medications inside a bag. Baggage coverage in a travel policy can fill that gap.
Personal liability is less discussed but potentially more serious. If you accidentally injure someone or damage property abroad, local legal systems may hold you financially responsible in ways your home liability coverage does not extend to. Some travel policies include personal liability protection for exactly this situation.
Rental vehicle damage is another gap travelers often discover too late. Credit card protections vary by card and country, and they generally exclude certain vehicle types and destinations. Our guide to rental reimbursement coverage explains what typical protections actually cover.
Medical evacuation costs can be catastrophic
Air ambulance transport from an international destination to the U.S. can exceed $100,000. Without evacuation coverage, that bill falls entirely on the traveler or their family.
Nonrefundable trip costs disappear with cancellation
Prepaid flights, hotels, tours, and cruises are often nonrefundable. A covered emergency without a policy means absorbing those costs with no recourse.
Domestic health insurance rarely covers foreign care
Most U.S. health plans have very limited or no international coverage, and Medicare provides essentially no benefits abroad, leaving travelers to pay out-of-pocket for any care received.
Personal liability abroad is unpredictable
Accidents involving injury to others or damage to property in foreign countries can result in legal and financial obligations that a traveler's home liability coverage does not extend to.
Baggage loss recovery is limited without coverage
Airline liability for lost checked bags has regulatory caps that may be far below the actual value of the contents. Without travel insurance, recovering the difference depends entirely on the airline's goodwill.
When skipping coverage is a calculated decision, not an oversight
There are situations where the risk calculation changes. A short domestic trip with fully refundable bookings and a domestic health plan that covers out-of-network care represents genuinely lower exposure. Travelers with substantial emergency savings may also decide they can self-insure against the scenarios most likely to occur.
The difference between single-trip and annual travel insurance plans matters here too. Frequent travelers may find that annual coverage changes the cost math considerably compared to buying per trip.
Whatever the decision, it should be deliberate. Reviewing what your existing health, homeowners, and credit card coverage actually provides abroad, in writing, before a trip departs, is the starting point. For a plain-language guide to what policies actually say, see what travel insurance fine print actually means.
This article is for general informational purposes only and does not constitute financial, insurance, legal, or medical advice. Coverage terms, exclusions, and costs vary by provider, policy, and destination. Consult a licensed insurance professional and verify current travel advisories with official government sources before traveling.