
Rental Reimbursement and Roadside Assistance: The Optional Coverages Worth Understanding
Key Takeaways
- Rental reimbursement only applies when your car is in the shop due to a covered insurance claim, not for routine maintenance or mechanical failures.
- Roadside assistance through an insurer differs from club-based programs; using it may generate a claim record depending on the provider.
- Both coverages typically cost a few dollars per month, but their value depends on how much you rely on your vehicle.
- Duplicate coverage from a credit card or auto club can make adding these through your insurer unnecessary.
- Policy limits for rental reimbursement are set per day and per claim, so always verify the daily cap against actual rental rates in your area.
Optional auto insurance coverages
Rental reimbursement and roadside assistance are add-on coverages you can attach to a standard auto insurance policy for an additional premium. Rental reimbursement pays toward a substitute vehicle while your car is being repaired after a covered claim. Roadside assistance covers on-the-spot services like towing, jump-starts, and lockout help when your vehicle breaks down.
These coverages are not required by any state and do not satisfy mandatory liability or minimum coverage thresholds. They are governed by the same policy terms and exclusions as your core coverages, so definitions of 'covered claim' vary by insurer.
What rental reimbursement actually covers
When your car is out of service because of a covered claim, rental reimbursement pays a portion of the cost to rent a substitute vehicle for the duration of repairs. The word 'covered' does a lot of work here. If your car is sideswiped and requires body work, rental reimbursement applies. If the transmission fails on its own, it does not.
The coverage has two monetary caps you need to know: a daily limit and a per-claim maximum. A policy might pay up to $40 per day and no more than $1,200 total. In cities where compact cars rent for $60 or more per day, you will pay the difference out of pocket. Before assuming the coverage is adequate, check current rental rates in your area against your policy's declared limits.
Rental reimbursement also does not cover every type of vehicle. Most policies reimburse for a standard rental car, not a truck, luxury vehicle, or SUV upgrade. If your insurer's appraiser determines repairs will take 12 days, you get the daily rate multiplied by 12, within the cap, regardless of how long the shop actually holds the vehicle.
For a broader view of how to keep optional coverages cost-effective over time, see managing auto insurance costs over time.
What roadside assistance covers and where it stops
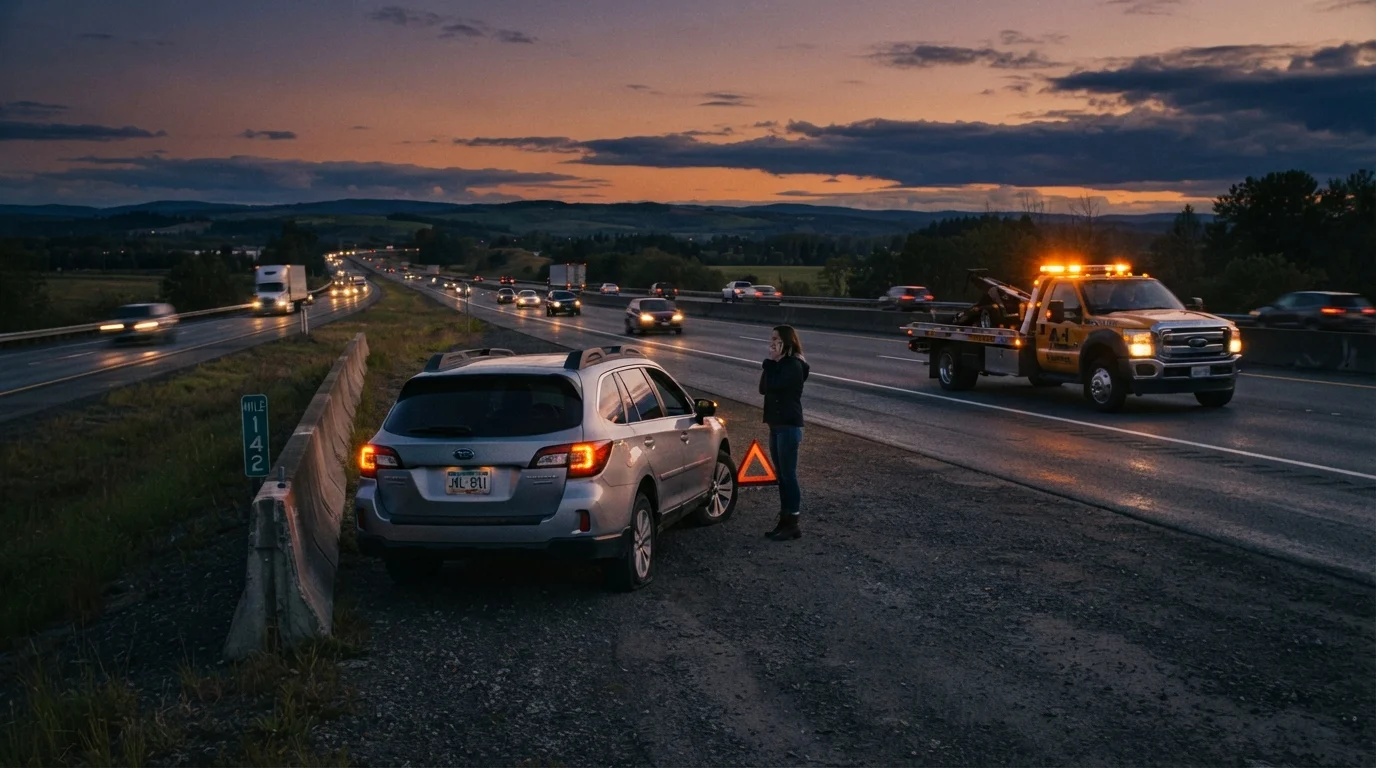
Roadside assistance through an auto insurer typically covers towing to the nearest qualified repair facility, battery jump-starts, flat tire changes (using your spare), lockout service when keys are locked inside the vehicle, and fuel delivery when you run out of gas. That last item usually comes with a caveat: the insurer pays for delivery but not the fuel itself.
Towing distance is often capped. A common limit is towing to the nearest repair shop or within a set number of miles, frequently 15 to 25 miles. If you break down far from a service center, you may pay for the extra distance.
Check for duplicate coverage before adding
Many credit cards and auto club memberships include roadside dispatch or rental discounts as built-in benefits. Pull out the benefits guide for any cards you carry and compare them against what an insurer's endorsement would add. Paying two premiums for the same service is a straightforward cost to avoid.
Roadside assistance does not repair the vehicle on the spot beyond basic interventions. A tow truck driver will not diagnose or fix an engine problem. The coverage gets you and the car to a safe location; what happens after that falls under your regular repair costs or other coverages.
If you already have roadside services through a credit card benefit or a standalone auto club membership, adding the coverage through your insurer may be redundant. Check what you already carry before paying an additional premium. The insurance coverage hub has broader guidance on identifying overlap across policy types.
How these coverages fit into your overall policy
Both coverages are endorsements, meaning they attach to an existing policy rather than standing alone. They are only available if you carry at least some physical damage coverage, either collision or comprehensive, depending on the insurer's rules. A liability-only policy generally cannot include rental reimbursement because there would be no covered repair scenario to trigger it.
The premium for each is modest, often $2 to $10 per month per coverage. Whether that cost makes sense depends on two factors: how dependent you are on your vehicle, and whether you already have equivalent protection elsewhere.
Drivers who own older vehicles with low market value sometimes drop collision and comprehensive coverage to reduce premiums. When that happens, rental reimbursement is no longer available either, since there is no covered physical damage claim to activate it. Understanding this relationship helps when you weigh coverage decisions as a vehicle ages. The article on usage-based and pay-per-mile insurance programs covers another dimension of how policy structure affects total cost.
This article provides general insurance information for educational purposes only, not personalized advice. Coverage terms, limits, and exclusions vary by insurer and state. Read your policy documents carefully and consult a licensed insurance professional for guidance specific to your situation.