
Key Takeaways
- Admitting fault at the scene can be used against you during the claims process, even if the statement was informal.
- Most auto insurance policies require prompt notification after an incident; delays can void coverage.
- Misrepresenting how you use your vehicle, such as for ridesharing, is grounds for claim denial.
- Failing to document the scene thoroughly weakens your position if the insurer disputes the details.
- Policy lapses from missed payments can leave you without coverage precisely when you need it.
Why the actions you take right after an accident matter
An auto insurance policy is a contract, and like any contract, it comes with conditions. Meeting those conditions is not optional. When a claim is filed, insurers review not just the incident itself but everything that happened before, during, and after it. Mistakes made in those windows give insurers legitimate grounds to reduce a payout or deny the claim entirely.
This is not about bad faith on the insurer's part. Most of the missteps that void claims are defined in the policy language that policyholders agreed to when they purchased coverage. The problem is that those terms are rarely read closely until something goes wrong. Understanding which actions create real legal and financial exposure can protect you when the stakes are high.
For a fuller picture of what to do at every stage of the process, see how to file a car insurance claim without making your situation worse.
Admitting fault at the scene of the accident.
Why it happens: The impulse to apologize after a stressful collision is natural, and drivers often say things like "I'm sorry, I didn't see you" without realizing those words carry legal weight.
Waiting too long to notify your insurer after an incident.
Why it happens: Drivers sometimes delay reporting because the damage seems minor, they hope to pay out of pocket, or they are unsure whether they will file at all.
Misrepresenting how the vehicle is used when taking out the policy.
Why it happens: Drivers underestimate how much vehicle use classification matters. Using a personal vehicle for delivery work or ridesharing without disclosing it is treated as a material misrepresentation.
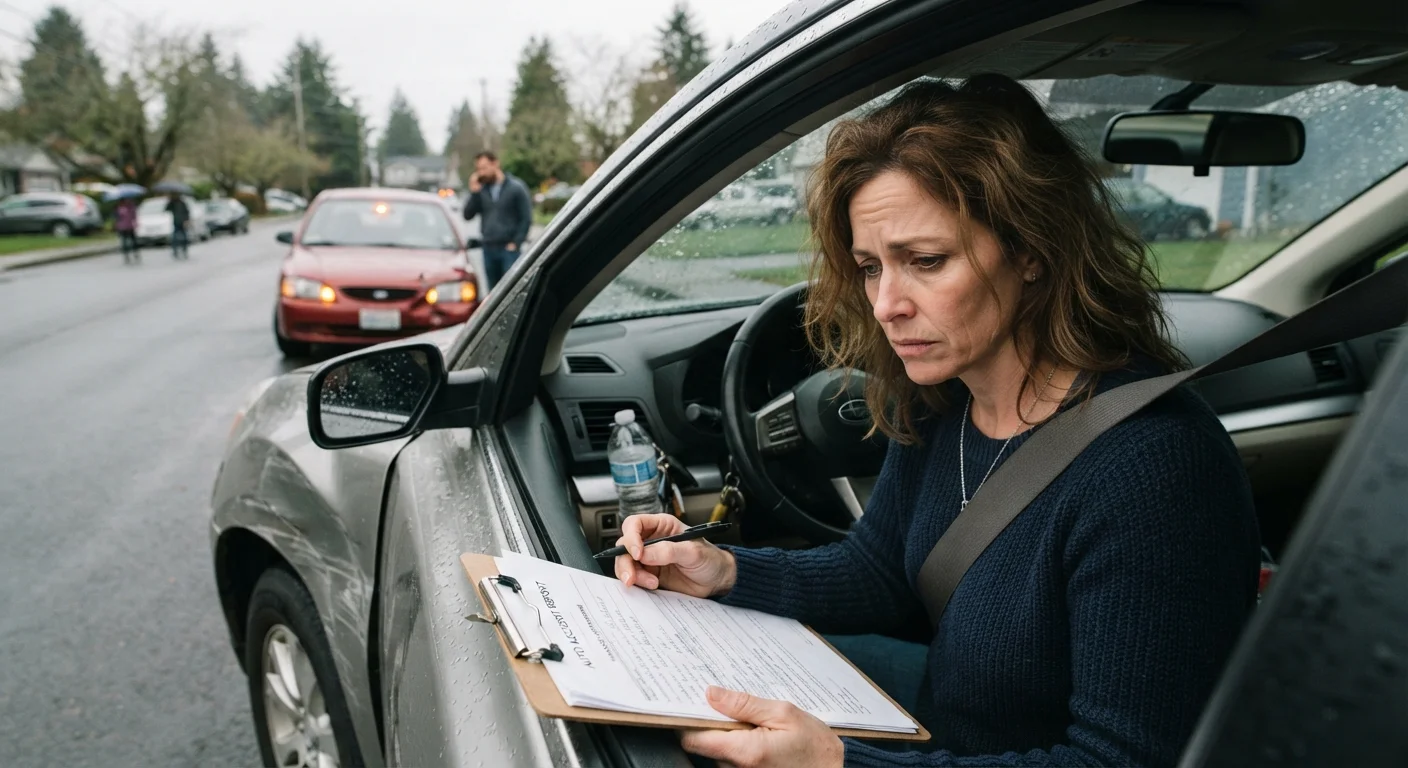
Failing to document the accident scene thoroughly.
Why it happens: Shock and confusion after a crash make systematic documentation feel like the last priority. Many drivers leave without photographs or witness contact details.
Letting the policy lapse due to a missed payment before an incident occurs.
Why it happens: Auto-pay failures, card expirations, and overlooked billing notices can cause a lapse without the driver realizing coverage has ended.
Having unauthorized repairs done before the insurer inspects the vehicle.
Why it happens: Drivers want their vehicle fixed quickly and may start repairs without understanding that the insurer typically needs to assess the damage first.
Protecting your claim before you ever need to file one
Most claim denials trace back to habits formed long before any accident occurs. Keeping a policy active and accurate is the foundation. That means paying premiums on time, updating your insurer when your circumstances change, and reviewing your coverage as your vehicle ages. Managing auto insurance costs over time explains how to adjust coverage without creating gaps that leave you exposed.
It also means understanding what your policy actually covers. Widespread misunderstandings, such as the belief that "full coverage" protects against every scenario, lead drivers to make decisions that leave them under-insured. Common insurance myths debunked addresses many of those assumptions directly.
If you live in a no-fault state, the rules governing who pays for what after a crash differ from traditional fault-based systems. No-fault insurance states explained covers what those differences mean for your coverage requirements and your options after a collision.
Recorded statements can hurt you
Insurers, including your own, may ask for a recorded statement shortly after an incident. You are generally not required to provide one immediately. Consult a licensed claims professional or attorney before agreeing to a recorded statement, particularly if liability is disputed or injuries are involved. Statements made without adequate preparation can be used to limit your payout.