
Sinking Funds: The Savings Technique That Stops Irregular Expenses From Derailing Your Budget

Key Takeaways
- A sinking fund is a dedicated savings pool for one specific, predictable future expense.
- Sinking funds prevent irregular costs from forcing you into debt or draining your emergency fund.
- The math is straightforward: divide the total cost by the number of months until you need it.
- Each sinking fund works best in its own labeled account or budget category so you do not accidentally spend the money.
- Automating monthly contributions removes the need to make a decision each month.
Sinking fund
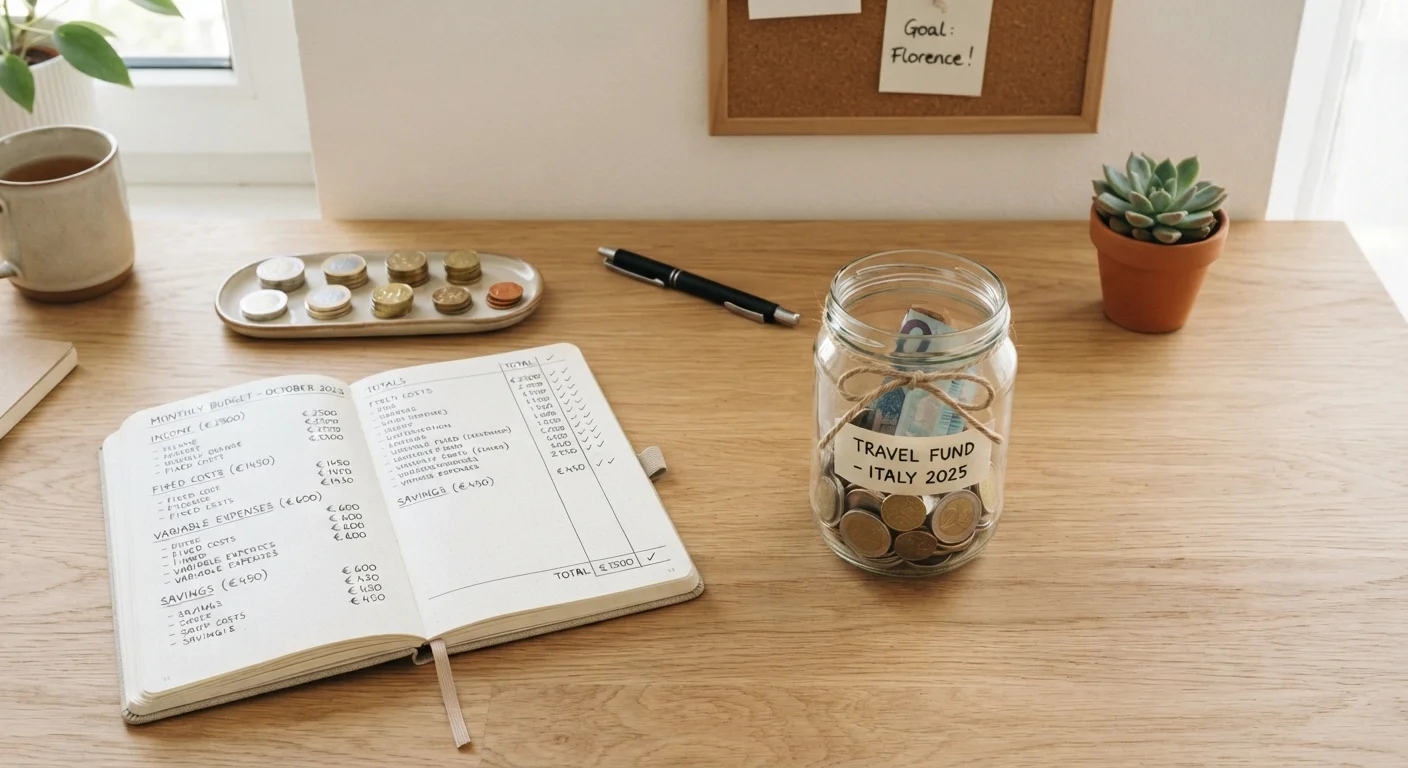
A sinking fund is money you set aside in small, regular amounts to cover a specific expense you know is coming. Instead of scrambling when a large bill arrives, you build toward it gradually. The name comes from accounting, where it describes a reserve built to retire a future debt or obligation.
In personal finance, sinking funds are distinct from emergency funds: they cover anticipated, non-recurring costs rather than unplanned emergencies.
Why irregular expenses break budgets
Most monthly budgets account for rent, utilities, groceries, and debt payments. What they often miss are expenses that are predictable in type but not in timing: the car registration that comes once a year, the dentist bill after insurance, the holiday gift budget that arrives every December. These costs are not surprises in the true sense. You know they will happen. What catches people off guard is the size of the lump sum when it finally lands.
Without a plan, the usual response is to pull from whatever is available: overdraft, credit card, or the emergency fund. Each of those options has a cost. Overdraft fees add up. Credit card balances carry interest. Tapping the emergency fund for a known expense leaves you exposed when something genuinely unpredictable occurs. A sinking fund breaks this pattern by spreading the cost across time.
A monthly budget review is a good place to surface which irregular expenses show up repeatedly and need their own fund.
How to set up a sinking fund
The calculation is simple. Identify the expense, estimate the total cost, and count the months until you need the money. Divide the total by the number of months. That figure is your monthly contribution.
For example: you expect to spend $600 on holiday gifts in December and it is currently June. That is six months away. $600 divided by 6 equals $100 per month. Transfer $100 to a labeled savings account each month, and the money is ready when December arrives.
Apply the same logic to annual insurance premiums, vehicle registration, home maintenance, a planned vacation, or any other known cost. For ongoing maintenance categories such as car repairs, a reasonable starting estimate for many vehicles is 1 to 2 percent of the car's value per year, though actual costs vary widely by vehicle age, make, and driving conditions.
Set up the transfer on payday
Scheduling your sinking fund contribution to move on the same day your paycheck arrives means it happens before discretionary spending can absorb it. Treat the transfer like any fixed bill: it goes out first, and you budget around what remains.
Automating the monthly transfer removes the decision entirely. Schedule the contribution on payday so the money moves before you have a chance to spend it elsewhere.
Which expenses are good candidates
Any expense that is predictable, non-monthly, and large enough to disrupt your cash flow qualifies. Common categories include:
- Vehicle registration and annual inspection fees
- Home and auto insurance premiums paid annually or semi-annually
- Medical and dental deductibles or co-pays
- Holiday and gift spending
- Planned travel
- Home maintenance and appliance replacement
- Back-to-school or annual subscription costs
Travel budgets deserve particular attention. Travelers who do not build a dedicated fund frequently undershoot the true cost of a trip. Common travel budgeting errors include underestimating local transport, entry fees, and tipping norms, all of which a sinking fund can absorb if the estimate is realistic from the start.
A sinking fund is not the right tool for genuinely unpredictable emergencies. For that, a separate emergency fund serves a different purpose. How large that emergency fund should be depends on factors beyond the standard three-month rule.
Keeping sinking funds organized
The most common problem is letting sinking fund money blend with everyday spending. If the $100 set aside for holiday gifts sits in your main checking account, it will likely get spent on groceries before December.
Separate accounts, even if held at the same bank, solve this. Many online savings platforms let you create named sub-accounts or spending buckets. Label each one with its purpose and target amount. Seeing a balance labeled "car maintenance: $340 of $500" is more concrete than a single undifferentiated savings total.
Once your sinking funds are running, they become a routine line item in your monthly budget check. Review each fund's balance against its upcoming deadline and adjust contributions if the target or timeline has changed. That ongoing review is what keeps the system accurate rather than just optimistic.
This article is for general informational and educational purposes only and is not personalized financial advice. Consult a qualified financial professional for guidance specific to your situation.