
| Minimum coverage required | Varies by state; most require liability at minimum (State DMV regulations) |
| Standard policy period | 6 or 12 months (Industry standard) |
| Total-loss threshold | Typically 70-80% of ACV, varies by state (State insurance regulations) |
| PIP required states | 12 no-fault states as of 2024 (Insurance Information Institute) |
Reading your policy with confidence
Auto insurance policies are legal contracts, and the language in them is precise by design. A word like "occurrence" or "exclusion" carries a specific meaning that controls whether a claim gets paid. Drivers who know these terms are better positioned to compare policies, ask the right questions, and avoid surprises at claim time.
This glossary covers the terms most likely to appear in a standard personal auto policy, a declarations page, or a claim letter. For a broader look at how insurance works as a financial product, see Insurance Decoded: What Every American Actually Needs to Know.
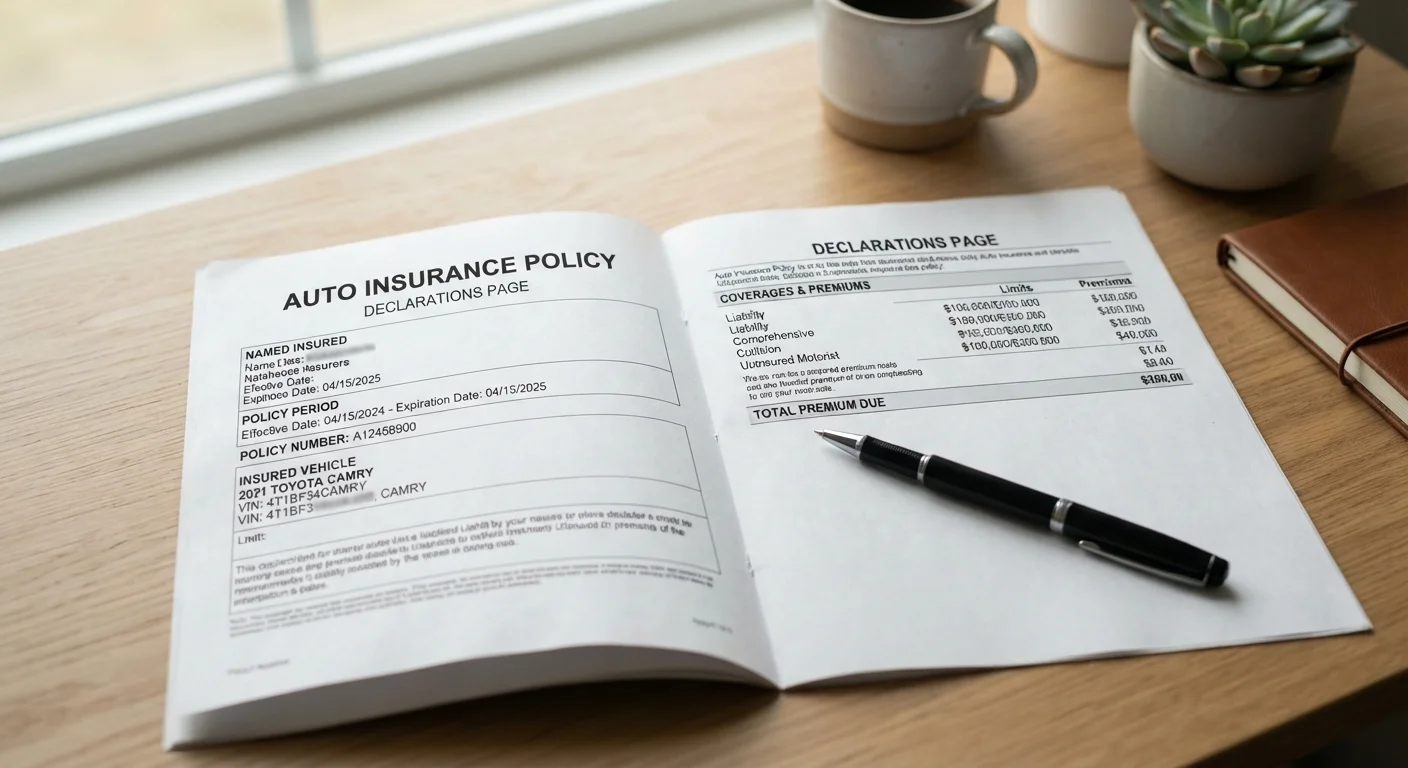
Declarations page
The summary sheet at the front of a policy listing the named insured, covered vehicles, policy period, coverage types, limits, deductibles, and premium. It is the first place to look when verifying what a policy covers.
Premium
The amount you pay the insurer for coverage, typically billed monthly, semi-annually, or annually. Premiums are calculated based on risk factors including driving history, vehicle type, location, and coverage selections.
Deductible
The dollar amount you pay out of pocket before your insurer covers the remainder of a covered claim. A $500 deductible on a $3,000 repair means you pay $500 and the insurer pays $2,500.
Coverage limit
The maximum dollar amount an insurer will pay for a covered loss. Limits are usually expressed per person and per occurrence for bodily injury, and as a single amount for property damage.
Liability coverage
Coverage that pays for bodily injury and property damage you cause to others in an at-fault accident. It does not cover your own injuries or vehicle damage.
Comprehensive coverage
Coverage for vehicle damage caused by events other than a collision, such as theft, fire, flooding, hail, or animal strikes. Subject to its own deductible.
Collision coverage
Coverage that pays to repair or replace your vehicle after a collision with another vehicle or object, regardless of fault. Subject to its own deductible.
Exclusion
A specific situation, person, or type of damage that a policy does not cover. Common exclusions include intentional damage, racing, and use of the vehicle for hire without a commercial endorsement.
Endorsement
A written amendment that adds, removes, or modifies coverage in a base policy. Endorsements appear on or alongside the declarations page and carry their own premium.
Subrogation
The legal right of an insurer to pursue a third party that caused an insurance loss in order to recover the amount paid on a claim. If successful, the insured may receive a portion of their deductible back.
Actual cash value (ACV)
The market value of a vehicle at the time of a loss, accounting for depreciation. Insurers use ACV to calculate total-loss payouts under most standard policies.
Personal injury protection (PIP)
Coverage that pays medical expenses, lost wages, and related costs for you and your passengers after an accident, regardless of fault. Required in no-fault states and optional in others.
Terms that affect what you pay
Several glossary terms directly control the dollar amounts on your bill and your payout after a loss. The relationship between your premium, deductible, and coverage limits is the foundation of every policy. Choosing a higher deductible lowers your premium but raises your out-of-pocket cost when you file a claim. For a deeper look at how these numbers interact, Premiums, Deductibles, and Copays: The Numbers on Your Policy Explained works through the math.
Valuation terms matter just as much. Whether your policy uses actual cash value (ACV) or agreed value determines how much you receive after a total loss. ACV subtracts depreciation; agreed value does not. The difference can run to several thousand dollars on an older or collector vehicle. Agreed Value vs Actual Cash Value vs Stated Value in Auto Policies covers all three methods in detail.
Endorsements are add-ons that expand or modify a base policy. Gap coverage, rental reimbursement, and roadside assistance are common endorsements. Each one appears on your declarations page with its own premium line, so you can see exactly what each addition costs.
Claims and fault terminology
Once an accident happens, a second vocabulary takes over. Adjusters use terms like subrogation, proximate cause, and reservation of rights in ways that directly affect claim outcomes. Subrogation is the right your insurer has to recover money from a at-fault third party after paying your claim. If your insurer recoups those funds, you may get part of your deductible back, depending on your state's laws and your policy terms.
A reservation of rights letter is a formal notice from your insurer that it is investigating a claim before confirming coverage. Receiving one does not mean your claim is denied, but it does mean you should read the letter carefully and consider whether to consult an attorney.
Fault terminology varies by state. In fault states, the at-fault driver's liability coverage pays for damages. In no-fault states, each driver's own personal injury protection (PIP) covers medical expenses regardless of who caused the accident. Knowing which system applies in your state affects how you file and what coverage you actually need.
If you are new to auto coverage overall, A First-Time Driver's Guide to Auto Insurance explains how these concepts fit into a complete policy.
This article is for general informational purposes only and is not personalised insurance, financial, or legal advice. Coverage terms, exclusions, and regulations vary by provider and state. Read your actual policy documents and consult a licensed insurance agent or adviser for guidance specific to your situation.